Here is a truth that most rugby bettors learn the hard way: your edge does not matter if you go broke before it plays out. You can be the sharpest analyst in every Six Nations preview thread, the person who correctly called Ireland’s Grand Slam and Fiji’s upset in the autumn tests, and still end the year with less money than you started with. The culprit is almost never bad analysis. It is bad bankroll management.
Bankroll management is the least glamorous topic in sports betting and comfortably the most important. It determines whether a losing streak is a temporary setback or a permanent exit from betting. It is the difference between the bettor who survives long enough to let their edge compound and the one who blows through their funds in February and spends the rest of the year watching rugby without any skin in the game.
Defining Your Bankroll
Before you can manage a bankroll, you need to define one. A betting bankroll is a fixed sum of money set aside exclusively for wagering — money you can lose entirely without it affecting your rent, your groceries, or your ability to sleep at night. This is not optional advice. It is the non-negotiable starting point of responsible betting.
The specific amount matters less than the discipline of treating it as a separate entity from the rest of your finances. Whether your bankroll is two hundred pounds or two thousand, the principles that follow apply identically. What changes is the absolute size of your stakes, not the percentage-based logic that governs them.
Once your bankroll is defined, you need a unit size. A unit is the standard amount you wager on a single bet, expressed as a percentage of your total bankroll. The consensus among professional bettors and serious hobbyists alike is that a unit should be between one and three percent of your bankroll. For a one-thousand-pound bankroll, that means individual bets of ten to thirty pounds. If that sounds small relative to the total, it is supposed to. Small unit sizing is the mechanism that keeps you solvent during the inevitable downswings.
The temptation to bet five, eight, or ten percent of your bankroll on a single match is powerful, particularly when you feel confident. A Friday night Six Nations fixture where you have done hours of analysis and believe you have found genuine value practically begs for an oversized stake. Resist it. Confidence is not certainty, and a ten-percent bet that loses three times in a row cuts your bankroll by nearly a third. At two percent per bet, the same three-loss streak costs you roughly six percent — uncomfortable but entirely survivable.
Flat Staking: The Baseline Approach
Flat staking is exactly what it sounds like: you bet the same fixed amount on every wager regardless of how confident you feel or how strong you believe the value to be. If your unit is twenty pounds, every bet is twenty pounds. The Six Nations decider and a midweek URC match between two sides with nothing to play for both get the same stake.
The obvious appeal of flat staking is simplicity. There is nothing to calculate, nothing to second-guess, and no room for emotional escalation. When you have just lost three bets in a row and are itching to chase your losses by doubling up on the next, flat staking removes the temptation by removing the decision. The stake is the stake.
The less obvious appeal is that flat staking is remarkably resilient to the kind of overconfidence that plagues bettors. If you are not as good at identifying value as you think you are — and statistically, most bettors are not — flat staking limits the damage from your worst bets. You never risk disproportionate amounts on the wagers where your edge is imaginary.
The downside is equally straightforward: flat staking does not optimise returns. If you genuinely have a larger edge on some bets than others, a flat stake treats all bets equally and leaves money on the table. A two-percent-value bet and a ten-percent-value bet both get the same twenty pounds. For bettors who can reliably distinguish between levels of edge, this is suboptimal. For bettors who cannot — which is most people — flat staking’s protective properties outweigh its inefficiency.
The Kelly Criterion: Optimal but Unforgiving
The Kelly Criterion is the mathematically optimal staking strategy for a bettor with a known edge. Developed by John Kelly at Bell Labs in 1956, the formula calculates the exact fraction of your bankroll to stake on a bet based on your estimated probability of winning and the odds being offered.
The formula is: stake percentage equals (probability times odds minus one) divided by (odds minus one). If you believe a team has a 60 percent chance of winning and the bookmaker offers decimal odds of 2.10, Kelly says to stake (0.60 times 2.10 minus 1) divided by (2.10 minus 1), which works out to approximately 23.6 percent of your bankroll. That is a large bet, and therein lies the problem.
Full Kelly staking produces extreme volatility. The strategy maximises long-term bankroll growth under perfect conditions, but those conditions require your probability estimates to be precisely correct. In rugby union betting, they never are. You are estimating win probabilities based on incomplete information — team news released 48 hours before kick-off, weather forecasts that change, and the inherent randomness of a sport where a single forward pass call can swing a match by fourteen points.
This is why most professionals who use Kelly do so at a fraction — typically quarter-Kelly or half-Kelly. Quarter-Kelly divides the recommended stake by four, producing a 5.9 percent bet in the example above instead of 23.6 percent. The growth rate is slower but the ride is dramatically smoother, and you maintain a meaningful buffer against estimation errors. Half-Kelly splits the difference: faster growth than quarter-Kelly, more volatility, but still far more forgiving than the full formula.
The practical challenge with any Kelly variant is that it requires you to assign a probability to every bet. That is harder than it sounds. Deciding that Ireland have “about a 55 percent chance” of covering a seven-point handicap against Scotland is one thing. Deciding whether it is 55, 57, or 52 percent matters when the formula translates those differences into meaningfully different stake sizes. If you do not trust your probability estimates to within a few percentage points, fractional Kelly may still introduce more noise than flat staking.
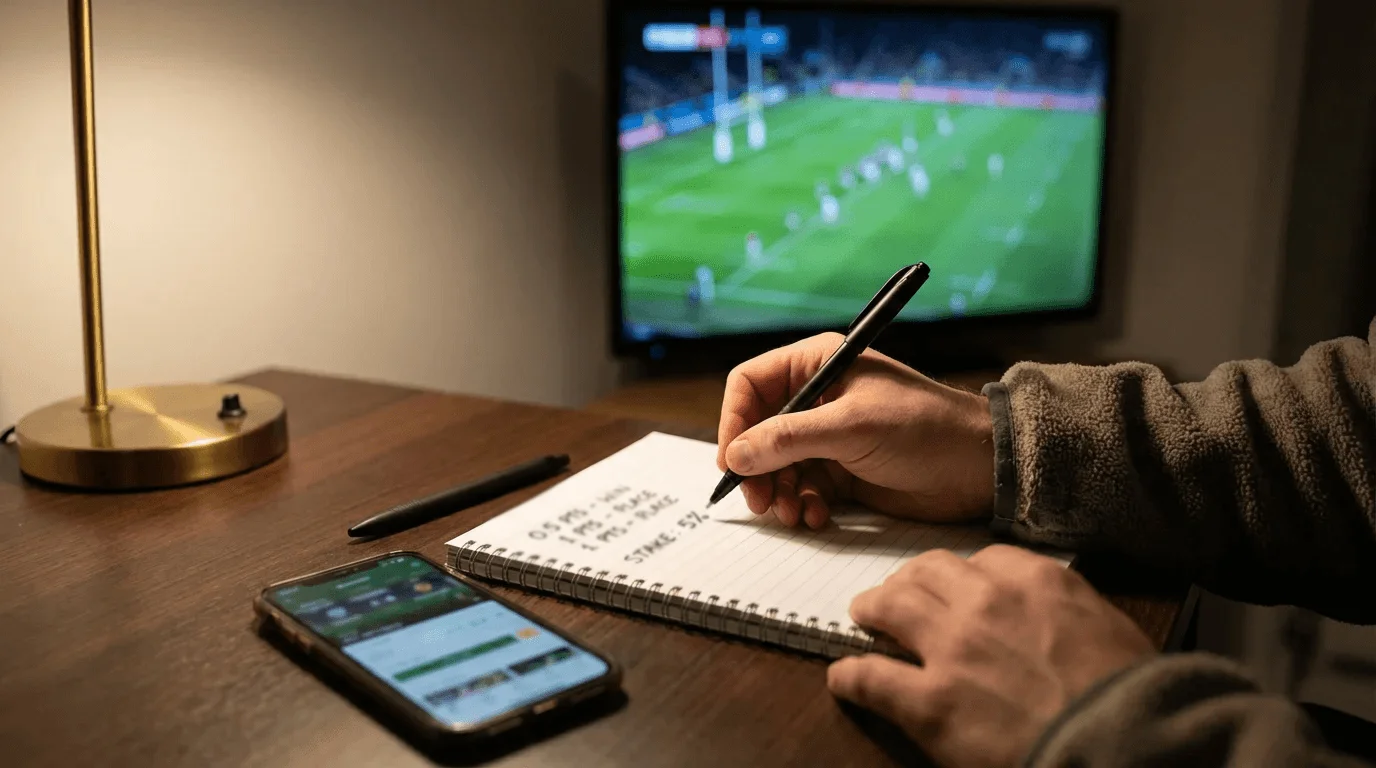
For rugby bettors specifically, a practical middle ground is to use three fixed stake tiers instead of a continuous Kelly output. Your standard unit for typical bets, a half-unit for lower-confidence plays, and a one-and-a-half-unit bet for your highest-conviction wagers. This captures the core Kelly insight — bet more when you see more value — without demanding precision that most bettors cannot deliver.
Surviving Losing Streaks
Every rugby bettor, no matter how skilled, will experience losing streaks. The question is not whether they happen but how long they last and how you respond. A bettor hitting at 55 percent on fair-odds bets — which is genuinely excellent — will still experience runs of eight or ten consecutive losses at some point over a season. If each of those losses was a two-percent unit, the total drawdown is 16 to 20 percent of the bankroll. Painful but manageable. If each was a ten-percent unit, you are effectively finished.
The psychological dimension is where most bettors break. After five or six losses, the urge to increase stakes becomes almost physical. The reasoning feels logical: you have been losing, so you are “due” for a win, and a bigger stake on the next bet will recover some of the damage. This is the gambler’s fallacy dressed in sensible clothes, and it has destroyed more bankrolls than any tactical misread ever has.
The antidote is mechanical discipline. Define your staking plan before the season starts, write it down, and follow it without exception. When the losing streak hits — and it will — your plan is already made. You do not need to make decisions under emotional pressure because the decisions are already made. Bet your unit, record the result, move on. The maths will do the rest over a sufficient sample size, provided you survive long enough to see it.
A useful mental reframe is to think in terms of seasons rather than individual weekends. A single Six Nations round has five matches. A Premiership season has over a hundred. If your approach has a genuine edge, it reveals itself over hundreds of bets, not dozens. The losing streak that feels catastrophic in week three of February is noise on a chart that stretches from September to June. See also betting mistakes.
When to Resize and When to Walk Away
Your bankroll is not static. If your betting is profitable, it grows. If it is not, it shrinks. The question is whether and when to adjust your unit size accordingly.
The conservative approach is to resize monthly or at natural breakpoints — the start of a new tournament, the beginning of the club season, the transition from autumn tests to Six Nations. Recalculate your unit as one to three percent of your current bankroll and continue. If you started with a thousand-pound bankroll and it has grown to twelve hundred, your unit increases from twenty to twenty-four pounds. If it has shrunk to eight hundred, your unit drops to sixteen. This gradual adjustment keeps your risk exposure proportional to your current capital.
The aggressive approach is to resize after every bet, which full Kelly technically demands. This is impractical for most people and unnecessary for recreational bettors. The gains from continuous resizing over periodic resizing are marginal, and the bookkeeping burden is real.
There is also a harder question that bankroll management forces you to confront: what if you are not a winning bettor? If your bankroll has declined by 30 percent or more over a sample of at least 200 bets, the evidence is pointing toward a negative edge rather than bad luck. At that point, the responsible action is to stop, review your process, and identify whether you have a genuine analytical edge or merely an expensive hobby. No staking plan can turn a losing strategy into a profitable one. Bankroll management keeps you alive, but it does not create skill.
The Uncomfortable Maths of Compounding Discipline
The payoff for disciplined bankroll management is not dramatic. It is not a single weekend where you turn five hundred pounds into five thousand. It is a grinding, incremental process where two-percent edges compound over months and years into meaningful returns. A bettor with a three-percent return on investment staking two-percent units across a thousand bets in a season turns a thousand-pound bankroll into roughly sixteen hundred. Not life-changing money, but not imaginary either — and critically, achieved without ever risking financial ruin.
Compounding only works if the bankroll survives long enough to compound. That is the entire point. Every staking decision you make is a vote for or against your own longevity as a bettor. The bettor who stakes two percent per bet and grinds out a 55-percent hit rate will be around next season and the season after that. The bettor who stakes ten percent per bet on “sure things” might have a spectacular weekend in February and an empty account by April.
The boring choice is the profitable one. That is the uncomfortable truth of bankroll management, and it is worth accepting as early in your betting career as possible. Bankroll management on rugby union betting.
